
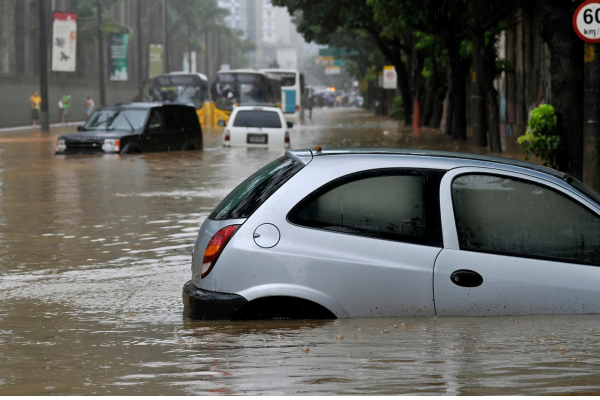
When your home or business suffers a disaster, whether from fire, water, wind, mold, or storm, the priority is to protect your property and recover what you have lost. However, the real challenge comes later: filing an insurance claim and obtaining fair compensation.
In this article, you will discover how to maximize every penny of your claim and why having a public adjuster can make the difference between receiving compensation… or being left with the loss.
Translated with DeepL.com (free version)
1. What to do in the first 24 hours after the disaster
Key actions that make a difference from the outset
The first 24 hours are crucial. During this time, you should:
- Prioritize your family’s safety and evacuate if necessary.
- Contact emergency services if there are electrical, structural, or health hazards.
- Document the damage BEFORE moving or repairing anything.
- Make only temporary repairs to prevent further damage (such as covering a broken roof with a tarp).
Do not contact your insurance company without clear evidence and without knowing your rights.
📞 Ideally, you should first contact a Public Adjuster for advice from the outset.
2. How to properly document damages
Visual and written evidence to support your claim
Una buena documentación puede marcar la diferencia entre una compensación completa… o un pago injusto. Asegúrese de:
- Take high-quality photographs and videos from multiple angles.
- Record dates, locations, and details of each affected area.
- If possible, save damaged items (do not throw them away).
- Inventory affected belongings, including approximate value and date of purchase.
A public adjuster can help you create a technical report that is much more robust than any document you could produce yourself.
3. What your policy actually covers (and what it doesn’t)
Understanding your coverage is your best weapon.
Most homeowners have not read their entire policy or do not understand the fine print. Some damages are often excluded or have specific conditions.
- Examples of common coverage:
- Damage from fire, smoke, or mold (if recent).
- Internal flooding (such as broken pipes).
- Damage from storms or hurricanes.
But there are nuances: for example, not all policies cover rain flooding if there is no prior structural damage.
A public adjuster interprets your policy and helps you claim everything you are legally entitled to.
4. Why the first insurance offer is almost never the best
And how can we negotiate fairer compensation?
Insurance companies protect their interests. That’s why the first offer is almost always less than what you really need to repair your property.
They have adjusters who work for them, and their goal is to minimize the payout.
You need an adjuster who works for you.
A public adjuster prepares realistic estimates of restoration costs, presents detailed evidence, and negotiates with the insurance company until you get what’s fair.
5. How a public adjuster can increase your compensation by up to 30% or more
Key ally in your claim
A public adjuster is a licensed professional who represents homeowners in the claims process. Their sole objective: to help you obtain the highest possible compensation.
What do they do for you?
- Review your policy in detail.
- Inspect the damage with technical expertise.
- Prepare realistic reports and estimates.
- File and follow up on your claim.
- Negotiate with the insurance company until the best result is achieved.
Studies show that homeowners who hire a public adjuster receive an average of 30% to 70% more in compensation.
6. Common mistakes that can cost you thousands
Avoid them before it’s too late.
🚫 Not documenting the damage properly.
🚫 Making complete repairs before the adjuster arrives.
🚫 Signing contracts with the insurance company without carefully reviewing the terms.
🚫 Not consulting a professional from the outset.
These mistakes can reduce your compensation or invalidate your claim entirely.
This guide is designed to help you avoid them and make informed decisions.
7. Lista de verificación descargable para tener todo listo antes de llamar al seguro
Antes de contactar con su aseguradora, asegúrese de tener a mano:
✅ Fotografías y videos de cada zona afectada
✅ Listado de pertenencias dañadas
✅ Recibos o facturas de pertenencias de valor
✅ Nombre y número de póliza de su seguro
✅ Notas sobre lo sucedido (fecha, hora, tipo de evento)
✅ Contacto de un Ajustador Público para que lo represente.
Programe su inspección gratuita
¿Sufrió daños por agua, incendio, moho o tormenta? ¡
No se enfrente solo al seguro! Nuestro equipo puede ayudarle desde la inspección inicial hasta la recuperación total de su propiedad.
Haga clic aquí para programar su inspección GRATUITA ahora:
https://api.leadconnectorhq.com/widget/bookings/freehomeinspectionsblog
Espacios limitados debido a la alta demanda. Servicio de emergencia 24/7.